Posted on
December 7, 2012
by
Tibor Bogdan
Canada’s Mortgage Housing Corporation is predicting there will be no housing downturn in Canada. CMHC is suggesting property sales will be softer next year and prices will be flatter, but no downturn will result. New housing starts in Vancouver will grow 4% next year.
“Balanced market conditions in most local housing markets will result in a slowing in house price growth as well,” said Mathieu Laberge, CMCH’s deputy chief economist.
The average price for a single detached home in the Vancouver region should reach $1.13 million by 2013. Investors are moving their money and focus away from single family detached homes to the condo market. With prices so high, most people seeking homes will have to look at condo offerings . Others will be forced to rent.
CMHC is a federally funded organization that provides various types of mortgage insurance to protect lenders from the risks of defaults by home buyers. It’s research unit monitors residential construction activity, housing sales and provides market outlooks for various sectors of the economy.
Posted on
December 4, 2012
by
Tibor Bogdan
News Release: December 4, 2012
HOME SALES DECREASE IN THE FRASER VALLEY; THOSE BUYING LOOKING FOR AFFORDABILITY
(Surrey, BC) – Property sales through the Fraser Valley Real Estate Board’s Multiple Listing Service® (MLS®) decreased by 19 per cent in November compared to the same month last year, moving from 1,120 to 905. Sales also decreased 14 per cent month-over-month compared to October 2012.
Scott Olson, president of the Board says, “Buyers can’t borrow as much as what they could prior to the mortgage rule changes, so we’re seeing our pool of prospective buyers shrink and we’re seeing a change in the price range they’re looking for.
“For three months in a row, we’ve seen a decrease in sales of detached homes $700,000 and up and greater demand for those $400,000 to half a million. Tighter credit conditions are having an impact on the market.”
In addition to the drop in sales in November, the number of new listings posted on the MLS® decreased by 11 per cent compared to last year and by 32 per cent compared to October. Olson observes, “This was a significant drop with last month ranking alongside November 2003 as the slowest for new listings in the last decade.
“It means that sellers are adjusting to conditions that favour buyers; great selection, houses are on the market longer and prices are lowering. If sellers don’t have to sell, they’re taking their home off the market.”
In the last six months, prices for all three residential property types combined have decreased by 1.4 per cent while year over year they’ve increased by 1.3 per cent. For single family detached homes, the benchmark price increased by 2 per cent in one year, going from $533,800 in November 2011 to $544,700 last month.
For townhouses, the benchmark price in November was $298,900, a decrease of 1.5 per cent compared to $303,600 during the same month last year. The benchmark price of apartments in Fraser Valley in November was $202,800, an increase of 2.6 per cent compared to $197,700 in November 2011.
The Board received 1,723 new listings in November compared to 1,926 during the same month last year, taking the number of active listings to 9,478, on par with November 2011.
For a detached home in the Fraser Valley, the average number of days to sell in November was 59, up five days from the same month last year. For townhomes, it was 70 days and apartments 74 compared to 52 and 72 in November 2011.
-------
The Fraser Valley Real Estate Board is an association of 2,855 real estate professionals who live and work in the BC communities of North Delta, Surrey, White Rock, Langley, Abbotsford, and Mission. The FVREB marked its 90-year anniversary in 2011.
Click here for the full package.
Posted on
November 23, 2012
by
Tibor Bogdan
Incidents of real estate fraud are increasing in Canada and homeowners and lenders are proving to be irresistible targets for fraud artists. Homeowners and lenders can protect themselves by obtaining a title insurance policy. The coverage provided in residential title insurance policies helps protect both innocent homeowners and lenders who might otherwise face huge financial losses resulting from title fraud.
What is Title Insurance?
The purchase of a home is for most people the most important financial transaction of their life. With an increasing number of fraud claims, more and more homeowners are protecting themselves with Title Insurance.
House Insurance protects homeowners from the physical damage or loss resulting from a fire or break in. Life insurance protects homeowners in the event of a death. Title Insurance protects the owner against losses incurred as a result of undetected or unknown title defects.
What does Title Insurance cover?
A title defect arises in a number of ways, but the defect that causes the most concern is real estate fraud. British Columbia has perhaps the most efficient land title system in the world (a “Torrens” system) but there are an increasing number of situations where fraud is committed. This can happen in a variety of ways.
With identity theft on the rise, it is not difficult for a fraudster to obtain legitimate identification claiming to be the true owner. The fraudster then deals with realtors and lawyers as if they were the owner, and proceeds to sell the property. Since the fraudster has legitimate identification, the realtor and lawyer are unaware of the fraud. Alternatively, the fraudster may work with a lender or mortgage broker, again with identification, to place a new mortgage on the property. In either situation, the true owner is unaware of the fraud and the fraudster absconds with the sale or mortgage funds.
Other typical examples include spousal impersonation and lawyer fraud.
In most cases the Assurance Fund of the Land Title Office may reimburse the true owner, but this may take several months and thousands of dollars in legal fees. Title Insurance may be quicker and less expensive.
In addition to protecting against title fraud, Title Insurance may cover violations of municipal by-laws, encroachments onto an adjoining property, realty tax arrears, existing work orders, lack of legal access to the property and unpaid strata assessments.
Read More of the original article here...
Posted on
November 21, 2012
by
Tibor Bogdan
The 18th annual REALTORS Care® Blanket Drive begins Nov. 26
VANCOUVER – The 18th annual REALTORS Care® Blanket Drive starts in less than one week. This year, the Blanket Drive runs from November 26 to December 3.
With the weather beginning to turn and charities and shelters facing the busiest time of the year, the need for Blanket Drive donations remains high. As always, we’re looking for gently used blankets, sleeping bags, warm winter clothing and jackets; in addition to new socks and underwear.
“After almost two decades in our communities, it’s amazing to see the level of support the Blanket Drive attracts and the difference it makes,” says Scott Olson, President of the FVREB. “Our regular donors have made this the largest warm clothing drive in our region and now with social media, we’re building even more awareness.
“Every pair of gloves, coat, sweater or blanket goes to someone who needs it. No donation is too small. The more we receive, the more we can help."
People are encouraged to bring donations to any one of the participating real estate offices across the Lower Mainland. Donations stay within the communities in which they are donated, or if the volumes are too large, go to charities in greatest need in neighbouring communities.
Each year, the Blanket Drive collects enough donations to help protect about 20,000 vulnerable people in our region from the cold, wet winter. Since 1995, the Blanket Drive has supported at least 185,000 people.
To see a list of drop-off locations, charitable recipients and items most needed, go to:
www.blanketdrive.ca
www.facebook.com/blanketdrive
www.twitter.com/FVREB or www.twitter.com/REBGV (#RCBD)
Posted on
November 9, 2012
by
Tibor Bogdan
Once in a while I have a client wanting me to look for a property where the seller is willing to rent out the property with the option to purchase it at a later date.
I don’t have to tell you that this scenario does not apply within a seller’s market when the properties are selling fast, for top dollar.
But this does become a plan “B” for people that:
- Have financial difficulties such as no down-payment or too much debt.
- Have employment difficulties (have a good job but not enough time on the job to get a mortgage from the lender.)
- Have bruised credit, but are working on improving it and hoping that they will succeed within a certain time frame.
There are a few common misconceptions that people have in regards to the structure of Rent-to-Own.
Misconceptions:
- Often buyers believe that the rent amount that they pay to the seller will be considered as a down payment in the near future.
-Reality: Only part of your monthly rent will go toward the down payment. Example: Let’s say that you are paying $2,000 rent for a house that would normally rent out for $1,500/month. This means that $500/month is going to your saving account towards your down payment.
- If I decide not to go ahead with the contract I can get all my money back.
-Reality: Depending on how the contract is structured, there is a good possibility that you will forfeit all of your money if you don’t go ahead with the contract.
Let’s look at the risks and rewards for this kind of a purchase.
Risks:
- What happens if after renting for a set term you re-apply for a mortgage and you are declined again? Likely you will lose your hard earned/saved cash and your contract will be terminated.
- What if the seller (that owns the property and title) gets him/herself into a legal battle, tax problems, or divorce and clearing the title becomes impossible for some time?
- What if the market value of the property declines to the point that the lender refuses to finance it?
- Who reimburses you for your improvements made to the home while living there?
- Who pays for the taxes, insurance…etc.
- Are you being asked for an upfront fee from the sellers?
Rewards:
- Renting to own gives you extra time to save money towards purchasing the home.
- If you’re bad at saving, rent-to-own is like a regimented savings plan.
- If you’re self-employed, you have time to establish your business financially.
- If the home is not to your liking, you can walk away. *as per contract agreed upon
- You can try out homeownership in a very realistic manner.
Rent to own is certainly a less that traditional route to homeownership, but for some people it bridges a difficult gap. The best rent-to-own scenario would be between a buyer and seller who trust one another implicitly and who understand the risks involved. Be realistic; if you choose to rent-to-own, make sure it is something you want and something you can afford to do.
In closing the best advice I can give you is this, Consult a professional before getting yourself into contract you don’t fully understand .
Written by Tibor Bogdan and Pat Pelletier
Posted on
November 2, 2012
by
Tibor Bogdan
Owning a home is one of the cornerstones of a solid financial plan. However, making mortgage payments for 20 to 30 years can take a huge bite out of your budget, even with low interest rates. A $300,000 mortgage at 3.29 per cent, amortized over 30 years will cost $161,300 in interest.
Yet it’s surprisingly easy to reduce your amortization – and the amount of interest you’ll pay. When you’re mortgage free, a big part of your budget will become available to help achieve your other financial goals.
Here are three ways to become mortgage free faster:
1. Make a lump sum payment.
A lump sum payment, or prepayment, reduces your outstanding principal. The sooner you can make a prepayment, the less interest you’ll pay over the long term. Your mortgage agreement specifies the maximum amount you can prepay each year (usually 10 to 25 per cent) and how often (usually once per calendar year) without penalty.
Coming up with a large lump sum - up to $75,000 on a $300,000 mortgage - is next to impossible for most people. But even a small sum – from a bonus or tax refund, for instance – can reduce your overall interest amount.
2. Increase the amount of your payments.
Most mortgage lenders allow you increase your payment by 10 to 100 per cent, but there may be a fee if you change it again during the calendar year. This option is easier than coming up with a large lump sum.
Paying an extra $100 a month on a $300,000 mortgage at 3.29 per cent over 30 years will save you more than $11,000 and reduce the amortization by 3 1/2 years.
3. Make more frequent payments.
Financial institutions offer a number of payment options. The standard ones are: monthly, semi-monthly, bi-weekly and weekly. Many people match the frequency to their pay periods for ease in budgeting.
If you decide to make more frequent payments, make sure you choose an accelerated option. Accelerated weekly and bi-weekly payments can save you thousands in interest charges because you’ll make the equivalent of one extra monthly payment each year. There is very little extra savings if you just switch to a more frequent payment without taking the “accelerated” option.
On the same $300,000 mortgage as above, a bi-weekly payment will save $289 in interest over the life of the mortgage. On the other hand, with an accelerated bi-weekly payment (an extra $50 per payment) you’ll save more than $18,000 over the life of the mortgage. You can save thousands in interest by paying off your mortgage as fast as your budget allows. Choose any one, all, or a combination of the prepayment options available to you. Contact your mortgage lender for your payment options and any penalties or fees you may be required to pay.
Tibor Bogdan
Posted on
October 5, 2012
by
Tibor Bogdan
~ Purchasing Real Estate from Non-Resident Sellers ~
Here is a Real Estate story that will send chills up your neck.
One day John and Mary drove through the neighborhood where they always wanted to live but they could not afford to buy their first home...or so they thought. A For Sale By Owner sign in front of the desirable home announced
that the price was more than reasonable, and after making a call and viewing the house they decided to write an offer on the property. The person that they were dealing with told them that it may take couple of days to get an answer since the owner was a non-resident. Withing a day the offer was accepted and John and Mary made
necessary arrangements to obtain a mortgage from their bank and inspect the property by a licensed inspector.
Once satisfied they removed all the subjects and a few weeks later they moved to their new home. So far so good!
The trouble began when the letter from CRA arrived asking them to pay the back taxes on the sale of the property.
They thought it was a mistake. Why should we pay taxes on the profit that the seller made when he/she sold them the house?
After meeting with a lawyer and accountant they were explained that since the seller did not pay the taxes and the buyers did not withhold 25% of the purchase price as they were required, John and Mary became liable for the taxes that seller did not pay.
I know what you are thinking right now,"This is stupid." I agree, it is not fair. But here is a chapter from the CRA rule book as presented by Manning Elliot LLP chartered accountants.
Anytime a purchaser is acquiring property from a non-resident, great care should be takes. The purchaser becomes liable for the tax liability in the event that the non-resident doesn't comply with the income tax rules in force at the time of the sale. Care should be taken to ensure that any vendor of real estate is a resident of Canada. The purchaser must be able to prove that they've made reasonable inquiry into the Vendor's country of residence to remove their own liability. A purchaser should consider having the vendor warrant verification of residence in
the sale/purchase agreement for the property to address this concern.
Wen purchasing property from a non-resident, ensure you have a copy of the certificate of compliance from CRA prior to completion. If not, you as a purchaser are required to withhold 25% of the purchase price from the sale and remit it to CRA on behalf of the vendor. Also, be sure the amount of the compliance certificate is the same as the agreed purchase price. Otherwise, CRA will hole the purchaser liable for the 25% of the amount by which the actual sale price exceeds the certificate of compliance.
So here is the lesson. Before you make one of your largest purchases in your lifetme, do your diligents and if you have no time to do it yourself then hire a competent Realtor to protect you from similar problems. I wish I could say that the story was fictional but I can't. Although the names are made up the story isn't.
Tibor Bogdan
Posted on
September 28, 2012
by
Tibor Bogdan
If you are thinking of selling your house, here is a chapter from my booklet, "How to sell your house for top dollar fast".
Curb appeal is a term used to describe how your home looks like from the exterior and how appealing it looks when viewed from the curb. This includes areas such as the lawn, patio, front door, exterior paint, trees, shrubs and more. In a simpler sense, curb appeal is what the buyers initially see the moment they step out of their car.
Curb appeal contributes greatly to the desirability of a home. Most real estate agents confirm that curb appeal can affect a buyer’s decision to purchase a home more than the square footage or the price of the home. It often means the difference between a house sitting for months or selling in a few weeks.
If your home is not particularly attractive from the outside, there are many ways to improve the curb appeal of your home without shelling out thousands of dollars in renovations. There are dozens of small, inexpensive home improvements that you can do to your house to add instant curb appeal. Adding curb appeal to your house not only makes it easier to sell, but it also gives your house that nice and finished look in which you can take pride in.
The following steps will help to quickly create curb appeal for your home.
1. Tidy up. Make sure you don't have old rusty junk lying around the yard, unless it is being used stylistically in a garden. Get rid of things that are just lying around. This would probably be the first step of improving the look of your lawn. Remove items such as old rope, boots, cracked pots, worn hoses, wrecked flower boxes and other things.
2. Trim up. Cut the grass and edge the borders with a weed trimmer. Take care to get rid of all weeds, including ones by the walls and around the mailbox post. Add a layer of mulch to cover up dull areas in the landscaping or flower beds.
3. Build a healthy and green lawn. Adding some starter sod can make a big difference very quickly. Sod can be bought at lawn and garden stores and comes in rolls or squares. After you lay it across your yard, water it well and you'll immediately have a lawn, with roots taking hold within two weeks.
4. Add some colour to your yard. Planting flowers will enhance the curb appeal of your home. Buying colourful plants that have already started blooming will immediately make a difference. They can either be planted in pots or in the ground. Use your imagination and choose flowers that bloom in colours that look good with your home.
5. Paint. Giving your home (trim and shutters too) a new coat of paint easily breathes new life into its appearance. However, make sure you select a colour palette that matches the architectural style of your home. For example, if you live in a historic home, you’ll want to stick to an authentic palette.
6. Update your front door. Greet guests in style with an eye-catching front door that makes a statement. You can find exterior doors in a variety of materials from traditional wood to sturdy steel. The key is to select a door that suits your home’s architectural style. If your current door is in good condition, you can make it stand out by painting it a bold colour or adding windows, sidelights, mouldings and more.
7. Illuminate paths and walkways with outdoor lighting. Install lighting fixtures that will complement the style of your home as well as help to create dramatic effects. Use fixtures with built-in motion detectors to enhance safety.
8. Add decorative accents. Top your exterior off with finishing flourishes such as trendy new house numbers that are clearly visible from the street. And while you’re at it, why not add a new mailbox? Or frame windows with new shutters?
If you would like to receive the entire report, click here and request a copy.
Tibor Bogdan
Posted on
August 17, 2012
by
Tibor Bogdan
When it comes to assessing a home's value, homeowners tend to be an optimistic bunch. Appraisers are a different story. They have to predict a realistic value for your home that the bank can use to extend credit to a borrower -- and that number can make or break your sale or refinance.
Appraisers say the following five areas are where homeowners often misjudge the worth of their house.
1. The Outside:
The appraiser sees: Overgrown bushes and chipped paint. What he does: Slices as much as 3% off the value of an average-size home. Why: Curb appeal is important. And an unkempt yard is a sign that there may be other issues. A good-looking lawn and bushes imply that you also take care of the internal systems in the house. Moreover, the more meticulous your neighbors are about grooming, the more your appraiser will downgrade the value of your home. If a lot of the nearby properties are professionally maintained, the one that sticks out like a sore thumb will get a harder adjustment than in a subdivision where there's more variation.
2. Basic systems:
The appraiser sees: A brand-new roof. What he does: Nothing.
Why: Just as a knee replacement won't make you look 20 years younger, a new roof, furnace, or boiler isn't considered an improvement to your home. That said, if your roof is in disrepair, replace it: Signs of leaks or discoloration can knock a significant amount off the home's value. When people buy a home, they expect the roof to be working, So while a new one isn't an added feature, it will help your chances of a sale.
3. The basement:
The appraiser sees: A recently finished basement with a half bath. What he does: Adds about 2% to the value of the home. Why: Yes, your finished basement adds value -- but don't expect it to count like first-floor space. The addition of a bedroom and quarter bath on the ground floor could increase your home's value by up to 20%, especially if you've got only one other bathroom.
4. The market:
The appraiser hears: Two nearby homes just went into contract above their asking prices. What he does: Nothing. Why: While a Realtor might pump up a home's asking price based on the sense that the market is "hot," by and large, appraisers are bound by the data of recent comparable sales.
5. A remodel:
The appraiser sees: An expensive, custom-made, built-in entertainment center. What he does: Makes a negative adjustment to the valuation. Why: "Cost doesn't equal value,". Renovations that are at all trendy -- or not in keeping with the historical period of the home -- will be assessed at the cost of ripping them out. Timeless improvements, on the other hand, such as a deep sink or new wooden cabinets in the kitchen, will add value. So if you're thinking of remodeling, ask a local real estate agent to tell you what's on the wish list of today's buyers.
Sincerely,
Tibor Bogdan
Posted on
August 10, 2012
by
Tibor Bogdan
 ~ What's the right mortgage? ~
For some weeks now, Bank of Canada governor Mark Carney, Finance Minister Jim Flaherty and most of the major Canadian banks have been warning that the record low interest rates of the past several years are over, and that a hike - perhaps even several - is on the horizon. At the same time, the banks have been offering truly incredible deals on long term fixed rate mortgages, some of them barely higher than prime.
So all of this leaves the variable-rate mortgage holder with the inevitable question: Is it time to lock in from a variable to a fixed rate? Well, as it turns out, the answer is a indisputable, unequivocal - maybe.
For every expert who says that absolutely, you should lock in now while rates are still low, there's another who argues just as confidently that rates are likely to stay put at least till the end of the year, and only a fool would give up a great variable. Here's the essential case both in favour and against locking in; only you can decide which argument feels right to you.
Read more:
http://www.vancouversun.com/business/decision+debt+What+right+mortgage/6910440/story.html#ixzz23AKOTab8
Sincerely,
Tibor Bogdan
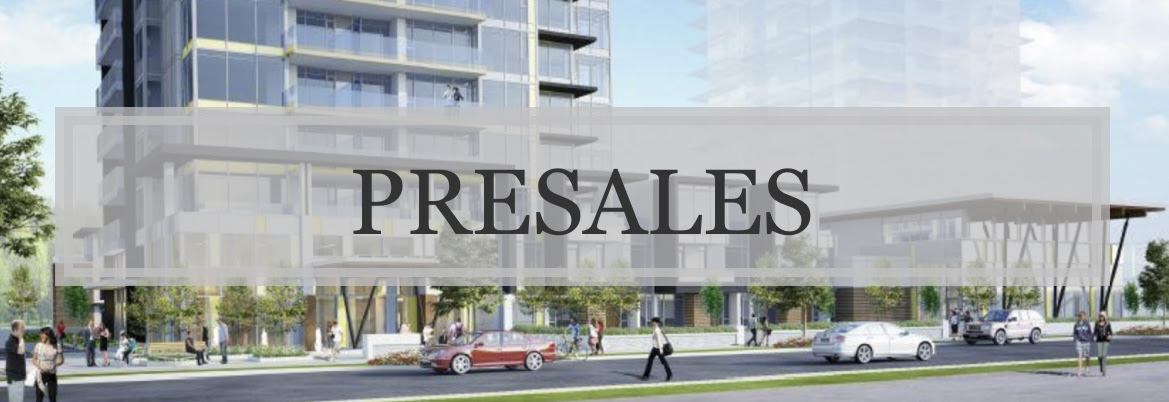 What is a pre-sale? Example scenario: When the developer intends to build an apartment building and applies for financing, the bank will grant financing under certain conditions. One of them will likely be a certain percentage of pre-sales the developer will need to secure before receiving the funds.
It is common practice for a developer to approach several real estate investors and offer them an opportunity to purchase units of the non-existent building at a discounted price, and on good terms.
Once the number of pre-sales is accomplished, the developer goes ahead with the construction, which will likely take two years or longer to complete. During construction, their marketing team offers the remainder of the units for sale at market value to the public.
If you are a RE investor, you know that it is preferable to be buying at the pre-sale prices, not market value prices.
The question is, how do you get the invitation to buy a pre-sale?
In the past many years, investors have made substantial income by buying at wholesale prices and selling at retail prices even before they needed to complete their purchase. I saw many of them lining up and sometimes even camping overnight in front of the sales center to get a chance to buy at lower prices, but not everyone was lucky enough. You needed to be well-connected to get an opportunity, and you had to act fast.
Today is a bit of a different story. Several projects in the Lower Mainland and Fraser Valley offer really good prices and incentives to secure a unit now and complete the purchase two or three years later. The list of incentives varies from one project to the next. Besides attractive prices, you can get low deposit amounts (5-15%), low or no assignment fees, free updates, a mortgage rate buy-down program, extra parking and more.
A month ago, I helped a few of my clients purchase a presale in Surrey that sold out in 2 days, and I know of another good developer that will be offering a few units for sale as well.
If you would like to know more about these opportunities, I would encourage you to call or email me, and I’ll be happy to send you details on those projects.
Kind regards,
Tibor Bogdan
Century 21 Creekside Realty Ltd.
45428 Luckakuck Way #190, Chilliwack, BC V2R 3S9
cell: 604-855-2521
|


 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.