Posted on
April 30, 2013
by
Tibor Bogdan
 With the warmer weather approaching, recreational properties are starting to get some attention. I am starting to get some inquiries about properties located in popular areas like Cultus Lake. These properties are not cheap, so if you are thinking of buying there consider all the aspects of purchasing a vacation property since they do come with both positive and negative aspects.
When choosing a property think about your long-term plans, and use that information to help you evaluate different properties. Consider why you want to own a property, and how long you want to have it. For example, do you want to be able to pass it down to your kids? This will help you take a long-term approach in evaluating different properties and finding the right one to best fit your needs.
If you are curious what Cultus Lake has to offer here are some of the properties near the lake http://goo.gl/6mVJf
Here are a couple of my favorites http://goo.gl/xo6O5
If you have any questions or would like to discuss this, please contact me.
Kind Regards,
Tibor Bogdan
Posted on
April 29, 2013
by
Tibor Bogdan
Here is a Real Estate story that will send chills up your neck.
One day John and Mary drove through the neighborhood where they always wanted to live but they could not afford to buy their first home...or so they thought. A For Sale By Owner sign in front of the desirable home announced that the price was more than reasonable, and after making a call and viewing the house they decided to write an offer on the property. A person that they were dealing with (not a realtor) told them that it may take a couple of days to get an answer since the owner lived abroad and was a non-resident. Withing a day the offer was accepted and John and Mary made necessary arrangements to obtain a mortgage from their bank and inspect the property by a licensed inspector. Once satisfied they removed all the subjects and a few weeks later they moved to their new home. So far so good!
 The trouble began when the letter from CRA (Canada Revenue Agency) arrived asking them to pay the back taxes on the sale of the property. They thought it was a mistake. Why should we pay taxes on the profit that the seller made when he/she sold them the house? After meeting with a lawyer and accountant they were explained that since the seller did not pay the taxes and the buyers did not withhold 25% of the purchase price as they were required, John and Mary became liable for the taxes that seller did not pay.
I know what you are thinking right now,"This is stupid." I agree, it is not fair. But here is a chapter from the CRA rule book as presented by Manning Elliot LLP chartered accountants.
Anytime a purchaser is acquiring property from a non-resident, great care should be takes. The purchaser becomes liable for the tax liability in the event that the non-resident doesn't comply with the income tax rules in force at the time of the sale. Care should be taken to ensure that any vendor of real estate is a resident of Canada. The purchaser must be able to prove that they've made reasonable inquiry into the Vendor's country of residence to remove their own liability. A purchaser should consider having the vendor warrant verification of residence in the sale/purchase agreement for the property to address this concern.
When purchasing property from a non-resident, ensure you have a copy of the certificate of compliance from CRA prior to completion. If not, you as a purchaser are required to withhold 25% of the purchase price from the sale and remit it to CRA on behalf of the vendor. Also, be sure the amount of the compliance certificate is the same as the agreed purchase price. Otherwise, CRA will hole the purchaser liable for the 25% of the amount by which the actual sale price exceeds the certificate of compliance.
So here is the lesson. Before you make one of your largest purchases in your lifetime, do your diligents and if you have no time to do it yourself then hire a competent Realtor to protect you from similar problems.
I wish I could say that the story was fictional but I can't. Although the names are made up, the story isn't.
Sincerely,
Tibor Bogdan
Posted on
April 26, 2013
by
Tibor Bogdan
This past 7 days we had 46 new listings. 27 Residential detached and 19 condominiums/town homes.
Here are all the new listings by the price ranges:
Residential Detached:
$300,000 - and under Click Here: http://goo.gl/RBuie
$301,000 to $400,000 - Click Here: http://goo.gl/AeUMn
$401,000 to $500,000 - Click Here: http://goo.gl/SJM4D
$501,000 to $600,000 - Click Here: http://goo.gl/1dGUw
$601,000 and up - Click Here: http://goo.gl/JRzT5
Residential Attached:
$250,000 and less Click Here: http://goo.gl/yFJiu
$251,000 and up Click Here: http://goo.gl/MOuFK
If you'd like to see any of these homes, I'm holding an Abbotsford House Tour weekly for the month of May.
Tours times are: Every Saturday 10am - noon
Click here to join us:
http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
--------
PLUS: Here are ways I can help you today:
Get A FREE Guide To Real Estate Prices
http://abbotsfordhomesearch.ca/guide-to-home-prices.html
Get FREE updates of all the new listings that come on the market
in any price range and area you choose:
http://abbotsfordhomesearch.ca/market-watch-update.html
Find Out How Much Your Home Is Worth
http://abbotsfordhomesearch.ca/home-evaluation.html
Weekly Tour of Homes
http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
Search for Homes
http://abbotsfordhomesearch.ca/recip.html/12976.searchform
Top 10 Mistakes Home Buyers Make
http://abbotsfordhomesearch.ca/top.html
How To Sell You Home for Top Dollar - FAST
http://abbotsfordhomesearch.ca/how-to-sell-your-home-for-top-dollar-fast.html
Sign Up For a First Time Home Buyer Seminar:
http://abbotsfordhomesearch.ca/first-time-home-buyers.html
Posted on
April 5, 2013
by
Tibor Bogdan
~ What is Mortgage Fraud and are you committing one without for even knowing it? ~
Mortgage fraud occurs when someone deliberately misrepresents information in order to obtain mortgage financing that would not have been granted if the truth had been known.
This can include:
-Misstating one's position or inflating one's income or length of service at their job;
-Misstating employment status (i.e. salaried/full time versus contract, part time, hourly or commission-based or self-employed);
-Misrepresenting the amount and/ or source of the down payment;
-Purchasing a rental property and misrepresenting it as owner-occupied;
-Not disclosing existing mortgage and/or debt obligations;
-Misrepresenting property details or omitting information in order to inflate the property value;
-Adding co-borrowers who will not be residing in the home and do not intend to take responsibility for the mortgage.
Another common form of fraud is when a con artist convinces someone with good credit to act as a "straw buyer."
A straw buyer is someone who agrees to put his or her name on a mortgage application on behalf of another person. In return for their participation, straw buyers may be offered cash or promised high returns when the property is sold. Often, straw buyers are deceived into believing they will not be responsible for the mortgage payments. Borrowers who misrepresent information and straw buyers who allow a property to be purchased in their name are committing mortgage fraud and will be responsible for any financial shortfall in the event of default. They may also be held criminally responsible for their misrepresentation.
(This was reported recently by Vancouver Sun.)
If you have any questions or would like to discuss this, please contact me.
Tibor Bogdan
Posted on
March 28, 2013
by
Tibor Bogdan
Abbotsford Market-Watch Newsletter for March 28, 2013. This week 61 new listings in the past 7 days.
---scroll down to view the listings
~ When your purchase is not properly represented, many things can go wrong! ~
Here is a case to learn from...This happened in 2005 (during a very hot market).
Mark and Sandy bought a new house in Chilliwack directly from the builder. They agreed on the contract price, terms and the completion dates. The house was about 6 weeks from being fully finished.
Due to the lack of representation many items in the contract were omitted.
Two weeks after the family moved into their new house, they found a letter from a local law firm informing them that a lean was placed on their title. The lean holder was a plumbing company that did the plumbing.
It turned out that the builder never paid the plumber for their work and apparently had no intention to do it now that the house had sold. The plumber demanded his $7,800 or else.
This is Unfair! Why should we pay for the plumbing twice!?
When we bought the house, the plumbing was included wasn’t it? These were their words when I meet them, to see if I can advise them on a solution.
This whole issue could have been avoided if the contract was properly drafted.
When new construction homes are sold, we protect the buyer by withholding 10% of the value of improvements for 55 days from the time the occupancy permit is issued. Example: If the cost to build the house is $ 250,000 then the buyer’s lawyer would withhold $25,000 and keep it in his trust account for 55 days. If there were any unpaid debts or contract invoices the contractors have 55 days to place a lean on the property.
So in this case, if the plumber had come with a request to get his invoice paid then there would have been money to pay him.
In the end, Mark and Sandy did solve their problem but this experience left them bruised. They no longer trust a handshake agreement and they promised me that they will always get a professional opinion before committing to any contract.
Tibor
----
This past 7 days we had 61 new listings. 34 Residential detached and 27 condominiums/town homes.
Here are all the new listings by the price ranges:
Residential Detached:
$300,000 - and under Click Here: http://goo.gl/xNwBc
$301,000 to $400,000 - Click Here: http://goo.gl/mK4aq
$401,000 to $500,000 - Click Here: http://goo.gl/oTpDY
$501,000 to $600,000 - Click Here: http://goo.gl/k8oR0
$601,000 and up - Click Here: http://goo.gl/vBU7Q
Residential Attached:
$250,000 and less Click Here: http://goo.gl/TSdHR
$251,000 and up Click Here: http://goo.gl/ftyLJ
If you'd like to see any of these homes - I'm holding an Abbotsford House Tour weekly for the month of April.
Tours times are: Every Saturday 10am - noon
Click here to join us: http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
I'll be back next week with all the new listings.
Warmly,
Tibor Bogdan
--------
PLUS: Here are ways I can help you today:
Get A FREE Guide To Real Estate Prices
http://abbotsfordhomesearch.ca/guide-to-home-prices.html
Get FREE updates of all the new listings that come on the market in any price range and area you choose:
http://abbotsfordhomesearch.ca/market-watch-update.html
Find Out How Much Your Home Is Worth
http://abbotsfordhomesearch.ca/home-evaluation.html
Weekly Tour of Homes
http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
Search for Homes
http://abbotsfordhomesearch.ca/recip.html/12976.searchform
Top 10 Mistakes Home Buyers Make
http://abbotsfordhomesearch.ca/top.html
How To Sell You Home for Top Dollar - FAST
http://abbotsfordhomesearch.ca/how-to-sell-your-home-for-top-dollar-fast.html
Sign Up For a First Time Home Buyer Seminar:
http://abbotsfordhomesearch.ca/first-time-home-buyers.html
Posted on
February 22, 2013
by
Tibor Bogdan
Scroll down to view all the new listings for the past 7 days in Abbotsford.
A few days ago I was approached by a client with this question, "Do I need to have an inspection done when I am buying a condo?"
As a realtor I never discourage a buyer from the inspection report on the property they are purchasing. However, let me talk about the purpose of the inspection and once you understand it, you will be able to make better decision.
When you are buying a residential detached home (house), you hire an inspector to give an idea as of what kind of expenses you will be facing in the next few years in regards to the exterior, structure, and the roof. You also want to know the current state of the electrical and plumbing. This information will help you to determine the yearly maintenance budget since you own the whole building.
You do not need an inspector to tell you that the faucet is leaking, the switch is not functional or that the carpet is stretched. You can do all these things by yourself in about 30 minutes.
When you are buying a condo, keep in mind that you do not own the building. It is owned in common with other owners. Therefore your maintenance costs are already established and included in your monthly strata fee.
When you hire a regular inspector they will spend most of their time researching whether your faucet is leaking, or checking the light switch functionality.
If you decide to hire an inspector, ask them to perform the inspection on the building itself, especially if you suspect that the building may have some water penetration issues (you may have heard of the Leaky Condo Phase).
It's very important to read the strata documentation to research whether the building had any issues in the past and if there is any indication of future problems.
There are a few inspectors that specialize in determining the health of the building and they will be able to give you good idea if you are making right choice buying your new condo.
Have a conversation with your realtor about these issues and they will be able to point you in the right direction. If you don't have a Realtor, call me or leave a comment on this article.
Kind Regards,
Tibor Bogdan
----
This past 7 days we had 49 new listings.
25 Residential detached and 24 condominiums/town homes.
Here are all the new listings by the price ranges:
Residential Detached:
$300,000 - and under Click Here: none this week.
$301,000 to $400,000 - Click Here: http://goo.gl/HtjEC
$401,000 to $500,000 - Click Here: http://goo.gl/6oz8V
$501,000 to $600,000 - Click Here: http://goo.gl/nIVjx
$601,000 and up - Click Here: http://goo.gl/qNNzL
Residential Attached:
$250,000 and less Click Here: http://goo.gl/gMhqR
$251,000 and up Click Here: http://goo.gl/7Zstx
If you'd like to see any of these homes - I'm holding an
Abbotsford House Tour weekly for the month of February.
Tours times are:
Every Saturday 10am - noon
Click here to join us:
http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
I'll be back next week with all the new listings.
Warmly,
Tibor Bogdan
--------
PLUS: Here are ways I can help you today:
Get A FREE Guide To Real Estate Prices
http://abbotsfordhomesearch.ca/guide-to-home-prices.html
Get FREE updates of all the new listings that come on the market
in any price range and area you choose:
http://abbotsfordhomesearch.ca/market-watch-update.html
Find Out How Much Your Home Is Worth
http://abbotsfordhomesearch.ca/home-evaluation.html
Weekly Tour of Homes
http://abbotsfordhomesearch.ca/tour-abbotsford-homes.html
Search for Homes
http://abbotsfordhomesearch.ca/recip.html/12976.searchform
Top 10 Mistakes Home Buyers Make
http://abbotsfordhomesearch.ca/top.html
How To Sell You Home for Top Dollar - FAST
http://abbotsfordhomesearch.ca/how-to-sell-your-home-for-top-dollar-fast.html
Sign Up For a First Time Home Buyer Seminar:
http://abbotsfordhomesearch.ca/first-time-home-buyers.html
Learn How To Buy a Home With Zero Down Payment:
http://abbotsfordhomesearch.ca/zero-down-payment.html
PLUS: Here are ways I can help you today:
Get A FREE Guide To Real Estate Prices
http://www.SearchChilliwackHomes.com/area/chilliwack/guide.htm
Get FREE updates of all the new listings that come on the market
in any price range and area you choose:
http://www.SearchChilliwackHomes.com/area/chilliwack/marketwatch.htm
Find out about the best little-known loan programs available with
our FREE Home Loan Report:
http://www.SearchChilliwackHomes.com/area/chilliwack/homeloan.htm
Find Out How Much Your Home Is Worth
http://www.SearchChilliwackHomes.com/area/chilliwack/cma.htm
FREE Ebook for HomeSellers
http://www.SearchChilliwackHomes.com/area/chilliwack/seller.htm
Weekly Tour of Homes
http://www.SearchChilliwackHomes.com/area/chilliwack/tour.htm
Search for Homes
http://www.SearchChilliwackHomes.com/area/chilliwack/searchhomes.htm
Posted on
January 25, 2013
by
Tibor Bogdan
A very interesting case recently reminded me of the evil effects this clause can produce. Most (all really) banks have in their standard loan documentation.
When you sign loan papers at the bank, somewhere in there you are signing something that gives them the right to call in ALL of your loans, if you default on any one of them. Let me highlight this by a true, recent incident.
Couple own a home financed by a big bank (BB). Great credit history and NEVER missed a payment on the mortgage. They also have 2 Visa cards (the husband is the main borrower, so the main responsibility). Also a truck loan for the husband.
The relationship goes sideways. These things happen, that is life. Lawyers get involved. Her lawyer says, don’t pay that Visa card, and let him look after it. His lawyer says, no way let her pay. So, the ONE visa goes in default. All other borrowings are maintained as agreed by the husband.
The mortgage matures in February of this year. BB advised the client that they will not renew him because of the “bad credit”. Really, they are invoking the Cross Default clause where a default on one loan instrument, constitutes a default on all. The client never, ever missed a mortgage payment and they are calling the mortgage because of a $3,000 visa debt!!
Refinancing is not easy, almost impossible because of the credit, and because this is a property where they got in with 5% and now the value of the home is less than when bought. This has been a nightmare for the client where parental had to be given.
I am not suggesting that this will be invoked in all cases, however, it is there and the banks can use it as a hammer. Credit Unions too by the way.
My experience where couples separate is that there are never any winners in a see/saw battle where husband/wife dispute ownership of a credit card or loan debt. Keep paying and sort it out in court.
Moral: The old adage “don’t put all of your eggs in one basket” might well be appropriate here.
Posted on
December 21, 2012
by
Tibor Bogdan
~ Violinist ~
Washington, DC Metro Station on a cold January morning in 2007. The man with
a violin played six Bach pieces for about 45 minutes. During that time approx. 2 thousand people went through the station, most of them on their way to work.
After 3 minutes a middle aged man noticed there was a musician playing. He slowed his pace and stopped for a few seconds and then hurried to meet his schedule.
4 minutes later:
The violinist received his first dollar: a woman threw the money in the hat and, without stopping, continued to walk.
6 minutes:
A young man leaned against the wall to listen to him, then looked at his watch and started to walk again.
10 minutes:
A 3-year old boy stopped but his mother tugged him along hurriedly. The kid stopped to look at the violinist again, but the mother pushed hard and the child continued to walk, turning his head all the time. This action was repeated by several other children. Every parent, without exception, forced their children to move on quickly.
45 minutes:
The musician played continuously. Only 6 people stopped and listened for a short while. About 20 gave money but continued to walk at their normal pace. The man collected a total of $32.
1 hour:
He finished playing and silence took over. No one noticed. No one applauded, nor was there any recognition.
No one knew this, but the violinist was Joshua Bell, one of the greatest musicians in the world. He played one of the most intricate pieces ever written, with a violin worth $3.5 million dollars. Two days prior, Joshua Bell sold out a theater in Boston where the seats averaged $100.
This is a true story. Joshua Bell playing incognito in the metro station was organized by the Washington Post as part of a social experiment about perception, taste and people's priorities.
The questions raised:
*In a common place environment at an inappropriate hour, do we perceive beauty?
*Do we stop to appreciate it?
*Do we recognize talent in an unexpected context?
One possible conclusion reached from this experiment could be this:
If we do not have a moment to stop and listen to one of the best musicians in the world, playing some of the finest music ever written, with one of the most beautiful instruments ever made.
How many other things are we missing?
Credit given to the Washignton Post for this article.
Tibor Bogdan
Posted on
December 19, 2012
by
Tibor Bogdan
For your information, the following news release is being issued by the Fraser Valley Real Estate Board, Real Estate Board of Greater Vancouver and the Chilliwack and District Real Estate Board today.
BLANKET DRIVE WARMS THOUSANDS
VANCOUVER, BC – From the Ladner seniors who fundraised to buy socks to students in Richmond and Langley, the 18th annual REALTORS Care® Blanket Drive collected blankets and warm clothing to help over 19,000 working poor and homeless people across the Lower Mainland.
Hundreds of real estate offices acted as drop-off locations during the November 26 - December 3 event. REALTORS® picked up, sorted and delivered thousands of donations to over three-dozen charities from Whistler to Hope.
The Squamish Helping Hands Society organizes a variety of shelter and food programs to assist those in need and is a recipient charity of the Blanket Drive.
“The blanket and clothing donations we get not only help our clients, the act of giving itself recognizes a much deeper understanding of the human need there is in our communities and how important it is for us to take care of each other,” said Maureen Mackell, executive director.
That sentiment was echoed by Andy Kwak, executive director of The Salvation Army Centre of Hope in Abbotsford.
“Our mission is to bring warmth, nutrition and shelter to those who need it, so you can imagine how helpful hundreds of bags of clothing and blankets are to the people we serve. We really appreciate the effort that REALTORS® put into this drive and their support throughout the entire year."
Since 1994, the Blanket Drive has grown to become the largest collection of its kind in the Lower Mainland assisting over 205,000 people over those years. Donations come from REALTORS®, their clients, the general public, corporations, retailers, community groups and schools. Everyone works together to make the drive a success.
Posted on
December 14, 2012
by
Tibor Bogdan
Great article from The Money Sense ( online magazine )
If you’re a parent of a young adult whose home ownership dreams have been dashed, there is a way to help. In June, the maximum amortization period for insured mortgages was reduced from 30 to 25 years, making it even more difficult to manage monthly payments. But having a parent co-sign on the dotted line allows adult children with lower salaries to get into the housing market. It’s a trend that mortgage brokers expects to increase in response to the new rules. But is it a good idea?
Before you put your John Hancock on that mortgage form, make sure you truly understand your child’s financial situation. “There’s a power dynamic that exists when a parent is heavily involved with a child’s financial life, It’s only advisable if you truly trust your child and know for certain that he or she is responsible with money.”
If the child doesn’t pay the bills the relationship can be ruined, since the parent is on the hook, Parents also have to be in good financial shape themselves: if Mom or Dad has too many debts or bad credit, the lender will deny the loan, which could be embarrassing. Instead, brokers advise both parents and kids to be patient and wait until the child is able to qualify on his or her own. “To qualify for a mortgage,someone should be able to stand on their own two feet.”
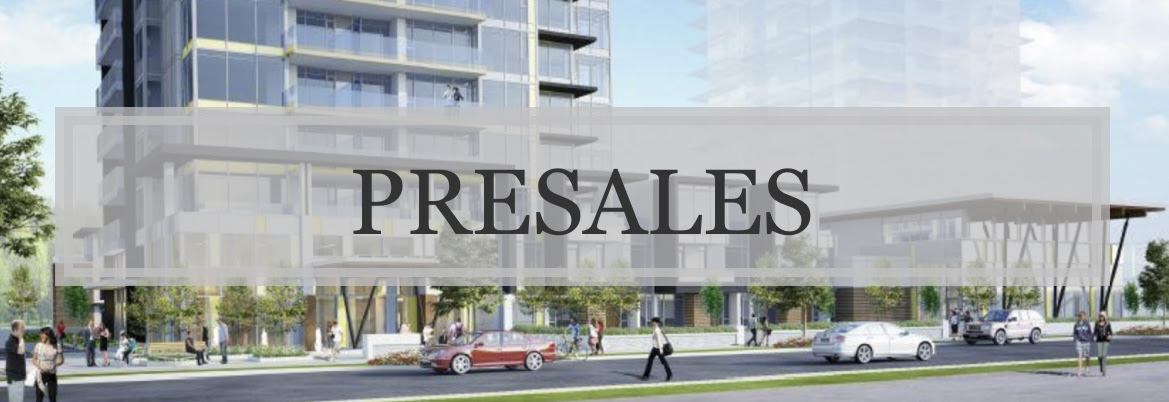 What is a pre-sale? Example scenario: When the developer intends to build an apartment building and applies for financing, the bank will grant financing under certain conditions. One of them will likely be a certain percentage of pre-sales the developer will need to secure before receiving the funds.
It is common practice for a developer to approach several real estate investors and offer them an opportunity to purchase units of the non-existent building at a discounted price, and on good terms.
Once the number of pre-sales is accomplished, the developer goes ahead with the construction, which will likely take two years or longer to complete. During construction, their marketing team offers the remainder of the units for sale at market value to the public.
If you are a RE investor, you know that it is preferable to be buying at the pre-sale prices, not market value prices.
The question is, how do you get the invitation to buy a pre-sale?
In the past many years, investors have made substantial income by buying at wholesale prices and selling at retail prices even before they needed to complete their purchase. I saw many of them lining up and sometimes even camping overnight in front of the sales center to get a chance to buy at lower prices, but not everyone was lucky enough. You needed to be well-connected to get an opportunity, and you had to act fast.
Today is a bit of a different story. Several projects in the Lower Mainland and Fraser Valley offer really good prices and incentives to secure a unit now and complete the purchase two or three years later. The list of incentives varies from one project to the next. Besides attractive prices, you can get low deposit amounts (5-15%), low or no assignment fees, free updates, a mortgage rate buy-down program, extra parking and more.
A month ago, I helped a few of my clients purchase a presale in Surrey that sold out in 2 days, and I know of another good developer that will be offering a few units for sale as well.
If you would like to know more about these opportunities, I would encourage you to call or email me, and I’ll be happy to send you details on those projects.
Kind regards,
Tibor Bogdan
Century 21 Creekside Realty Ltd.
45428 Luckakuck Way #190, Chilliwack, BC V2R 3S9
cell: 604-855-2521
|


 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.