Posted on
February 25, 2011
by
Tibor Bogdan
What is Short sale? Good question.
Short sale is when the sale proceeds do not cover the mortgage amount and the costs associated with the sale of the property.
So, if your mortgage payout is $300,000 and the buyer is paying you $280,000,it is a short sale. The difference in this sale is that the mortgage holder will have to be consulted before the deal becomes firm and binding. The lender will either have to take the loss of
$20,000 or arrange for a line of credit for the sellers.
It is rare to see a short sale, but down South it is a very common process. In the USA the short sales are coming on the market faster then the foreclosures and if they don’t sell fast enough they will become foreclosures. However, here in Canada short sales are very few since our Real Estate markets are more stable and our mortgage structure allows for the homeowners to renegotiate and restructure their mortgage rates and their terms every 5 years.
Have a story you would like to share, or a question about short sales? Leave a comment below, I would love to read them.
Tibor
Posted on
February 7, 2011
by
Tibor Bogdan
I am re-reading "The Seven Habits of Highly Effective People. In one chapter the author, Stephen Covey talks about how we tend to worry about everything in the world. We are concerned about our economy, political situation our job stability, interest rates and about our kids' future. We worry about what we eat, and drink. We are concerned about the prices, inflation, our retirement. Just to name a few.
It's quite overwhelming and the media is not helping us to reduce our levels of stress by bringing new concerns into our attention on an hourly bases; such as global warming, stock market crashes and live broadcasts from the war zone.
The author of the book suggests doing this.
Take all your concerns and write them down on a piece of paper and tag them as The Circle of Concerns. Then go through them one by one and ask yourself a question, "Is it within my power to do anything about this concern?" And if the answer is yes then write them down and tag them as Circle of Influence.
Soon you will see that out of so many concerns that occupy your mind at the present moment there are only a few that you yourself can influence and do something about it.
Proactive people focus their efforts in the circle of influence. They work on the things that they can do something about.
Reactive people, on th eother hand focus their efforts in the Circle of Concern.
So lets be Proactive and take control of our concerns. Let's start to work on our circle of influence rather than worry about our circle of concern.
This small adjustment in our attitude will have a calming effect in our everyday life and it makes us more effective and productive in our work and home.
Tibor Bogdan
Your Realtor for Life
Posted on
January 24, 2011
by
Tibor Bogdan
Two years ago I had a nice little house for sale in Mission. Didn’t take very long and I got a call from a couple that drove by and liked the house enough that they wanted to view it inside and out.
After the first viewing they arranged for a second one.
The decision to put an offer on the property was made the same day and few hours later we had an accepted offer on the property.
The financing was obtained with some difficulty but the contract became unconditional and we moved on to the completion stage.
So until now the whole process went relatively smooth.
It all changed one day before completion when I got an unexpected visit from Alex, my buyer.
“I don’t have enough money for a down payment can you help?" I pinched myself just to make sure I wasn't in the middle of a nightmare. The next thing I did was cancel all my appointments for that day since, Alex became my main priority.
There is no Realtor in this world that wouldn’t get goosebumps after hearing what I heard. You see, my sellers had already bought their dream property, and the sellers of that one already bought something else too. So if Alex would not complete the other 2 families would not be able to complete either.
Needless to say I was very motivated to help him. To make a long story short I was able to help them to find more $$$$ to complete the transaction but I never forget how I felt on that day.
In my heart I knew that they were overstretching their finances and they shouldn’t be buying a house.
Last week I got a call. "Hi Tibor it’s Alex remember me?" I replied, "I am sorry can you tell me more about yourself?"
"Remember, you helped us to buy a house 2 years ago?"
I remembered!
Alex said, "I have to sell now! Can you help me?"
I arranged an appointment to see him.
Here is what happened in the past 24 months.
He lost a job, got a second mortgage on the house to catch up on some big bills, then his wife couldn’t take the financial stress anymore so she left. Making the things worse the health issues he had made it impossible for him to find a new job. He stopped paying the mortgage payments and the bank started to apply pressure. That’s when he called me.
The point I am trying to make is this. His problems did not start 6 months ago. They only matured 6 months ago. He brought his problems with him 2 years ago when he bought his first house. He was not ready for a home ownership. It did not benefit him and it wont until he is ready for it.
Let’s learn form this Friends. Analyze your financial situation and your commitment to the better future and make sure that the home purchase propels you forward not backwards.
If you need help with this process call me. I can help!
Tibor Bogdan
Your Realtor for life.
Posted on
January 14, 2011
by
Tibor Bogdan
Let’s say that you have put an offer on a foreclosure property, and it is accepted by both parties. Before the court date is requested the Seller (usually a Bank) asks you to sign a document called a “Schedule A”.
What is a schedule A?
This is one of the most disgusting documents you will ever see. It says that you are willing to take the house “as is, where is” at the time of the possession (the time you will get the keys). If the house is no longer there, or is damaged, vandalized, burned, flooded, is missing all the appliances…it is YOUR problem!
Why would anyone vandalize the house you bought?
Well, you need to remember that the people living in the house before you get possession are no longer owners – they are tenants living there free with absolutely no obligations to maintain the property. Sometimes these tenants are quite angry that their house has been taken away from them.
Thankfully we live in a part of the world where these things are rare.
But it is a scenario that exists, so you should prepare for it rather than ignore it. Talk to your Realtor about how to avoid problems when buying a foreclosure.
Do you have other questions in regards to foreclosure properties?
Send me an email and I see if I can help.
tbogdan41@hotmail.com
Tibor
Posted on
December 31, 2010
by
Tibor Bogdan
Something To Think About. . .
Washington, DC Metro Station on a cold January morning in 2007. The man with a violin played six Bach pieces for about 45 minutes. During that time approx. 2 thousand people went through the station, most of them on their way to work. After 3 minutes a middle aged man noticed there was a musician playing. He slowed his pace and stopped for a few seconds and then hurried to meet his schedule.
4 minutes later:
The violinist received his first dollar: a woman threw the money in the hat and, without stopping, continued to walk.
6 minutes:
A young man leaned against the wall to listen to him, then looked at his watch and started to walk again.
10 minutes:
A 3-year old boy stopped but his mother tugged him along hurriedly. The kid stopped to look at the violinist again, but the mother pushed hard and the child continued to walk, turning his head all the time. This action was repeated by several other children. Every parent, without exception, forced their children to move on quickly.
45 minutes:
The musician played continuously. Only 6 people stopped and listened for a short while. About 20 gave money but continued to walk at their normal pace. The man collected a total of $32.
1 hour:
He finished playing and silence took over. No one noticed. No one applauded, nor was there any recognition.
No one knew this, but the violinist was Joshua Bell, one of the greatest musicians in the world. He played one of the most intricate pieces ever written, with a violin worth $3.5 million dollars. Two days before Joshua Bell sold out a theater in Boston where the seats averaged $100.
This is a true story. Joshua Bell playing incognito in the metro station was organized by the Washington Post as part of a social experiment about perception, taste and people's priorities.
The questions raised:
*In a common place environment at an inappropriate hour, do we perceive beauty?
*Do we stop to appreciate it?
*Do we recognize talent in an unexpected context?
One possible conclusion reached from this experiment could be this:
If we do not have a moment to stop and listen to one of the best musicians in the world, playing some of the finest music ever written, with one of the most beautiful instruments ever made.
How many other things are we missing?
Happy 2011 to you all !
Posted on
December 28, 2010
by
Tibor Bogdan
Making new friends was so easy when we were children. There were kids in the neighborhood to play with and classmates to hang out with. All through school and on into college, people were just there – people who became our friends.
That all changed when we entered the adult world. We may be surrounded by people in our community and/or work environment with whom we’re friendly, but they may not be people we form friendships with.
Sometimes friendships end because people move away, or people change, or they simply get too busy with family and work to do more than send a holiday card.
However in my opinion real friendships do not recognize distances and/or time. I have few good friends back in Slovakia where I lived for first 28 years of my life . Even after years of not being in contact with them when we meet it felt like the time did nothing to our friendship it is still there . We may look and even feel older and our interest may be different now , but we still feel connected.
However I grew up in the times when we actually meet our friends in person. We had no Cellphones to text each other, no Internet to send emails. The only time we were able to interact was when we did thinks together.
We live in a different world now.
I feel like We misuse word “ Friend “ these days. In the world of social media we place a label “Friend “ on anyone that sends us a request. Don’t get me wrong ,I am not saying that we should not be friends online , My point is that we should make the effort to get to know people in our so called “ Friend Circle” and see if we can form a real friendships with some of them
Use the social media for staying in touch with your real friends but also find new ones and make the effort to really get to know people . Take them for coffee ,visit them at work go to the gym together or for a golf game.
We are all unique in our own way . so let’s find out what is good and unique about our Face Book friends
I am sure you will be glad you did.
Tibor Bogdan
Posted on
December 14, 2010
by
Tibor Bogdan
Question from my client Darcie, “Should I be listing my house for sale in December?”
Great question Darcie - Experience shows that December is not the best time to sell a house.
Why?
The reason is that the market is not very focused and the only people that are selling are either desperate sellers that have to sell or unmotivated people that do not care when their house will sell.
To get a good price for your house I would recommend to list in the second half of January. By then, Christmas and New Year’s celebrations are over and everyone is focused and back to business.
However for the same reason, December can be an opportunity for the right person
If you are an investor or a first time buyer, December can be a very good time to find some bargain prices and great mortgage rates. In the past I helped a few of my clients/investors to acquire investment properties in December that appreciated 2-4% in less than 90 days. (Do the math on the $400,000 purchase they made…$8,000-16,000).
In Real Estate as in life, timing is everything. Talk to your Realtor about these issues and if you don’t have one, just comment bellow and I will get back to you with an answer ASAP.
Tibor
Posted on
December 10, 2010
by
Tibor Bogdan
It is easier than you might think!
This was a story reported by The Vancouver Sun last year.
Here is what happened recently to Norman Gettel. As a Vancouver Sun reporter Gillian Shaw explained how Gettel learned he no longer owned his Richmond bungalow when his tax bill failed to show up as usual.
A call to the B.C. Assessment Authority confirmed that he was no longer the registered owner and, to make matters worse, the land titles office advised that the new owner had put a $400,000 mortgage on his paid-off home, assessed last July at more than $600,000.
The mortgage is in default and CIBC Mortgages Inc. has demanded payment in full -- $403,034.95 plus interest of $53.18 a day and legal cost of $375 -- or it will "enforce its security" on the property.
How can this happen?
Here in BC we have probably the best title registration system called Torrens System of Land Registration.
There's nothing wrong with the system, which processes 14 million applications a year and keeps track of owners and lenders efficiently enough. But it cannot detect fraud.
So, how do we protect ourselves from the bad guys that are after your Real Estate? - The same way that we protect ourselves against other unforeseen dangers like fire, earthquakes and car accidents…we buy insurance. Title insurance that is!
How does it protect you and your investment?
The one-time premium for title insurance is approximately $250 and in the case mentioned above, if Norman would have had the title insurance he would not have had to hire an expensive lawyer. Plus, the fraudulent mortgage on his house would not be his problem. It’s a small price to pay for a piece of mind isn’t it?
Title insurance prevents crime as well; by carefully reviewing every transaction, they are able to detect patterns that indicate a fraud and then advise the lender not to release the funds.
Title Insurance does more than Fraud Insurance and if you want to know more about it write me a note and I will make sure you will get the answers to your question!
Tibor
Posted on
November 25, 2010
by
Tibor Bogdan
My question was this:
After a 3 week search we’ve found the perfect house for a young family. It is close to schools, close to work, has a great yard for the kids – perfect, except that it is outdated and needs some renovations. They only have the minimum 5% down payment. They want to renovate immediately after they get they keys but have no money for it. Is there some way to do this?
This was a reply from Pat Pelletier, Mortgage Specialist.
Yes. Absolutely. Since you are putting down 5% the mortgage has to be default insured by either CMHC or Genworth. They both have a program called “purchase plus improvements”. You have to do this with your Broker or your bank, but this will give you a bit of an education on the program.
Here is what happens. Say you buy the home for $300,000 (you have 5% down or $15,000). After you look at the home you estimate that you need a new kitchen, new floors and that this will cost you about $20,000. Note that before final approval, you will have to get formal quotes. Say you go to a large Home Renovation Centre and get a quote for both: total $20,000. $15,000 for kitchen and $5,000 for flooring.
You give these quotes to your Broker. So, now, the total is $300,000 plus the $20,000 or $320,000.00. This is sent to the bank & the insurer. If approved, then they will approve a loan of $304,000. ($320,000 less 5% - 16,000). Note that your down payment is now increased by $1,000.
Then you move in. Do the work and once the work is 100% done, the bank will send an inspector (at your cost) and if 100% done, will release the funds. So, you do the work first, before getting paid for it. You may be able to arrange a line of credit for this, or your contractor will accept getting paid at the end.
Here’s the kicker: the work needs to be done as on the quote, but does not necessarily be done by the person who gave you the quote. Example: say part of your quote was from a painter for $4,000 for paint & painting. Say you go to the Reno Centre and buy a few gallons of paint, and do it yourselves. You will be advanced the full $4,000 if the work is done as on the quote.
You can’t include chattels (fridge, stove, etc.) in these quotes. Those are called chattels and are not considered attached to the home, or structural.
For more information, please call or e-mail me.
Tibor Bogdan or Pat Pelletier
Pat: 604-850-5110
Tibor: 604-855-0800
Posted on
November 10, 2010
by
Tibor Bogdan
Often I am asked what is the best deal in the Fraser Valley.
Right now?
I'd have to say that you can’t beat new construction.
The HST had a negative impact on new construction and therefore there are many new and finished homes sitting, waiting for the past 3 months for a buyer. Many builders have reduced the prices to the point that they're effectively paying the HST for the buyer. Example: A home in East Abby in a desirable neighborhood sold in June (before the HST) for $564,000.
An identical home is on the market right now for $508,000 plus HST ($35,559).
That is over $21,000 less then the one for $ 564,000.
Where can you find the best deals? You can’t beat the Chilliwack market. You can buy a brand new home for under $425,000 and that will include the HST, appliances, blinds and more. I have not seen a more affordable market in the past 10 years.
On the Chilliwack homes that I mentioned, your monthly mortgage installments would be $1,615, providing that you have a 5% down payment. If you don’t have the down payment then talk to me I could help guide you in the right direction.
Take advantage of it! If you don’t know how, let me help you.
Tibor
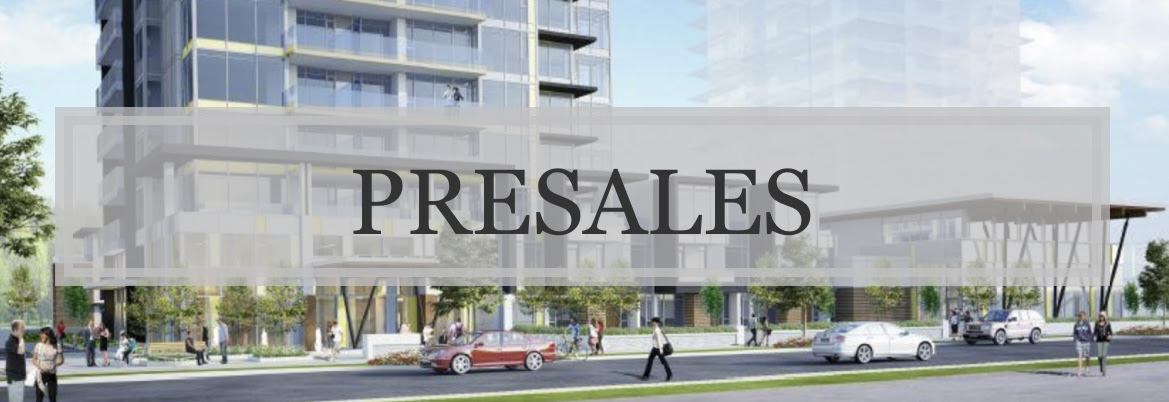 What is a pre-sale? Example scenario: When the developer intends to build an apartment building and applies for financing, the bank will grant financing under certain conditions. One of them will likely be a certain percentage of pre-sales the developer will need to secure before receiving the funds.
It is common practice for a developer to approach several real estate investors and offer them an opportunity to purchase units of the non-existent building at a discounted price, and on good terms.
Once the number of pre-sales is accomplished, the developer goes ahead with the construction, which will likely take two years or longer to complete. During construction, their marketing team offers the remainder of the units for sale at market value to the public.
If you are a RE investor, you know that it is preferable to be buying at the pre-sale prices, not market value prices.
The question is, how do you get the invitation to buy a pre-sale?
In the past many years, investors have made substantial income by buying at wholesale prices and selling at retail prices even before they needed to complete their purchase. I saw many of them lining up and sometimes even camping overnight in front of the sales center to get a chance to buy at lower prices, but not everyone was lucky enough. You needed to be well-connected to get an opportunity, and you had to act fast.
Today is a bit of a different story. Several projects in the Lower Mainland and Fraser Valley offer really good prices and incentives to secure a unit now and complete the purchase two or three years later. The list of incentives varies from one project to the next. Besides attractive prices, you can get low deposit amounts (5-15%), low or no assignment fees, free updates, a mortgage rate buy-down program, extra parking and more.
A month ago, I helped a few of my clients purchase a presale in Surrey that sold out in 2 days, and I know of another good developer that will be offering a few units for sale as well.
If you would like to know more about these opportunities, I would encourage you to call or email me, and I’ll be happy to send you details on those projects.
Kind regards,
Tibor Bogdan
Century 21 Creekside Realty Ltd.
45428 Luckakuck Way #190, Chilliwack, BC V2R 3S9
cell: 604-855-2521
|


 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.